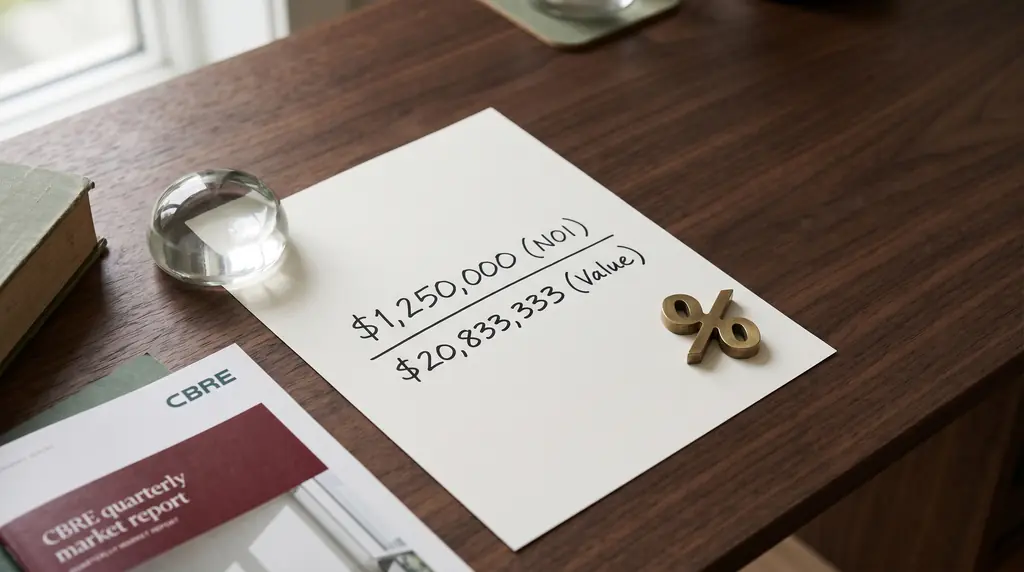
The Kitchener-Waterloo commercial real estate market in 2026 prices its core asset classes inside a tight, well-documented envelope: Downtown Office Class A at 6.00-6.75%, Class B at 6.50-7.25%; Industrial Class A at 5.75-6.50%, Class B at 5.75-6.50%; Multifamily High Rise A at 4.50-4.75%; Retail Strip (anchored) at 5.50-6.35% (CBRE Q1 2026 Canadian Cap Rates and Investment Insights, April 21, 2026). KW is one of only two Southwestern Ontario markets CBRE tracks by name in its national cap rate series (London is the other), which makes it among the most data-rich smaller markets in Canada. What is tightening: Trophy-adjacent industrial bids on supply tied to the Waterloo EDC pipeline, with Southwestern Ontario industrial availability down 40 bps year-over-year to 7.2% in Q1 2026 per Altus - the only region in Altus's Q1 2026 industrial update to post a year-over-year availability decrease. What is loosening: Class B office in the suburban submarkets, which trades roughly 100 bps wider than its Downtown Class A counterpart. Cambridge rolls up into CBRE's Kitchener-Waterloo bucket; there is no separate Cambridge cap rate series in any national report.
Key Takeaways
- CBRE's Q1 2026 Kitchener-Waterloo envelope: Downtown Office A 6.00-6.75%, Industrial A 5.75-6.50%, Multifamily High Rise A 4.50-4.75%, Retail Strip (anchored) 5.50-6.35% - the lowest-friction KW-specific numbers available on the open web.
- KW has no Downtown Class AA series in CBRE's national report - it is a Class A market with no AA. The asymmetry is invisible in national headlines but load-bearing for any practitioner valuing a KW office tower.
- Cambridge cap rates roll up into CBRE's Kitchener-Waterloo bucket and Altus's Southwestern Ontario industrial block - there is no separate Cambridge series. Cambridge supply, however, is tracked in named-park detail by Waterloo EDC.
- Southwestern Ontario industrial availability decreased 40 bps year-over-year to 7.2% in Q1 2026 per Altus - the only region in Altus's Q1 2026 industrial update to post a year-over-year decrease.
- The Canadian national all-properties average cap rate was 6.61% in Q1 2026 per CBRE; KW Downtown Office A sits 75 bps wider than the tight end of Toronto Downtown Class AA and 25 bps tighter than Toronto Downtown Class A, and KW Industrial Class A sits 75-125 bps wider than Toronto Industrial A.
The KW commercial market in 2026 - headline ranges by asset class
The table below is the CBRE Q1 2026 Kitchener-Waterloo cap rate envelope by asset class, with the Canadian national comparison alongside. The Q1 2026 report (published April 21, 2026) carries a full KW page; quarter-over-quarter, the office, industrial Class A, retail, and hospitality ranges held while multifamily edged higher. Cambridge and Guelph asset-class cap rates are not separately published - both roll up into the figures below or into Altus's Southwestern Ontario block.
| Asset class | Kitchener-Waterloo (CBRE Q1 2026) | Canada national avg | KW spread to Toronto (where applicable) |
|---|---|---|---|
| Downtown Office Class AA | N/A (no AA series in KW) | 6.79% (CBRE Q1 2026) / 6.59% (Altus Q4 2025) | n/a |
| Downtown Office Class A | 6.00 - 6.75% | Toronto Downtown A 6.25-7.00% per CBRE Q1 2026 | Toronto Downtown AA at 5.25-7.75%; KW Class A 75 bps wider on the tight end, 25 bps tighter than Toronto Downtown A |
| Downtown Office Class B | 6.50 - 7.25% | Toronto Downtown B 6.75 - 7.50% per CBRE Q1 2026 | n/a |
| Suburban Office Class A | 6.50 - 7.50% | - | n/a |
| Suburban Office Class B | 7.00 - 7.75% | - | n/a |
| Industrial Class A | 5.75 - 6.50% | 5.78% (CBRE national) | Toronto Industrial A at 5.00-5.25% - KW ~75-125 bps wider |
| Industrial Class B | 5.75 - 6.50% | 6.38% (CBRE national) | Toronto Industrial B at 5.25-6.00% - KW ~50 bps wider |
| Multifamily High Rise A | 4.50 - 4.75% | 4.51% (CBRE High Rise A) | n/a |
| Multifamily High Rise B | 4.50 - 5.00% | 4.83% (CBRE High Rise B) | n/a |
| Multifamily Low Rise A | 4.50 - 5.25% | 4.69% (CBRE Low Rise A) | n/a |
| Multifamily New Construction | 4.50 - 4.75% | 4.66% (CBRE New Construction) | n/a |
| Retail Regional | 6.00 - 6.50% | 6.44% (Altus Tier I) | n/a |
| Retail Power Centre | 6.00 - 6.50% | - | n/a |
| Retail Strip (anchored) | 5.50 - 6.35% | - | n/a |
| Hospitality (Downtown Full Service) | 8.00 - 9.25% per CBRE Q1 2026 | - | n/a |
Source: CBRE Q1 2026 Canadian Cap Rates and Investment Insights (April 21, 2026), Kitchener-Waterloo page. National averages: CBRE Q1 2026 report (office/industrial/multifamily) and Altus Group Q4 2025 Canadian CRE Investment Trends Survey (Tier I regional retail; the most recent ITS print). KW has no Downtown Class AA series and no High Street retail in CBRE's national report.
Where KW sits in the Ontario hierarchy: Toronto tighter, Ottawa wider, KW a Class A market in between
Ontario's three CBRE-tracked markets sort cleanly on cap rates. Toronto Downtown Class AA office trades at 5.25-7.75% in Q1 2026, a wide intra-AA range reflecting the gap between Trophy and standard AA. KW has no AA series - the top of its office stack is Class A at 6.00-6.75%, which sits roughly 75 bps wider than Toronto Downtown AA on the tight end and 25 bps tighter than Toronto Downtown Class A (6.25-7.00%). Ontario commercial cap rates sit on a national average of 6.61% per CBRE Q1 2026 (April 21, 2026), with the spread over the 10-year Government of Canada bond at 317 bps.
Industrial is the segment where Toronto and KW diverge most. Toronto Industrial Class A at 5.00-5.25% in Q1 2026 is among the tightest industrial prints of the major Canadian markets - only Vancouver, at 4.50-5.25%, prints lower. KW Industrial Class A at 5.75-6.50% sits 75-125 bps wider - a spread that reflects supply discipline more than demand weakness, given the Waterloo EDC pipeline (covered below) and Southwestern Ontario industrial availability that improved against the national trend in Q1 2026.
Ottawa wraps the wider end. Ottawa Downtown Class AA office at 6.25-6.50% sits at the tight end of Ottawa's stack; Class A is 6.75-7.75% and Class B is 7.50-8.50%. Ottawa office availability rose 170 bps year-over-year to 14.2% in Q1 2026 per Altus Q1 2026 office update, driven by shadow vacancies and PSPC disposal-plan adjustments. KW's office picture is materially healthier than Ottawa's on the demand side.
Industrial is KW's strongest segment, anchored by named Waterloo EDC supply and a Southwestern Ontario availability trend that bucked the national pattern
The Q1 2026 Southwestern Ontario industrial picture is the single most distinctive data point in this report. Per Altus, regional industrial availability sat at 7.2% in Q1 2026, down 40 bps year-over-year - the only region in Altus's Q1 2026 industrial update to post a year-over-year availability decrease. National industrial availability rose to 6.2% in Q1 2026 (+40 bps year-over-year) per Altus; JLL Canada Industrial Q1 2026 recorded national vacancy of 5.1% - the first decline since 2022 (Altus measures availability inclusive of sublet; JLL measures vacancy; the figures are not directly comparable). Southwestern Ontario Q1 2026 completions: 3 buildings totalling roughly 424,000 square feet, approximately 75% available at delivery per Altus.
The supply pipeline below the headline number is named and trackable. Waterloo EDC's real estate inventory identifies the active industrial parks driving the regional picture: iPort Cambridge, iPort Franklin, The Link Cambridge (105 Allendale Road, within Cambridge's IP Park), IP Park, Generation Park, 400 Bridge Street, and the Wilmot Industrial Park site. The mix spans speculative Class A logistics product (iPort Cambridge, The Link) and serviced, shovel-ready land with mid-bay units (IP Park, Generation Park). Q1 2026 industrial completions in Southwestern Ontario delivered into this pipeline, and the availability print improved despite the new supply - a signal that absorption is keeping pace with delivery.
For the cross-Ontario industrial picture - Toronto-tight, GTA-9.8M sf-under-construction, Southwestern Ontario improving - see Ontario industrial cap rate trends. The Cambridge commercial real estate market picture is anchored almost entirely by this industrial pipeline.
Office and multifamily - KW-specific dynamics
Office. KW's office stack is Class A at the top (6.00-6.75% downtown, 6.50-7.50% suburban) with no Downtown AA series. The named Class A inventory is concentrated downtown: GloveBox at 120 Victoria Street South, 50 Queen Street North (50Q), 55 King Street West, and 590 Riverbend Drive per Waterloo EDC. Suburban Class B at 7.00-7.75% is the widest print in the KW office stack and reflects the pattern visible nationally - flight-to-quality concentrates demand in the top of the stack, leaving older suburban inventory wider. Canadian office availability was 15.4% in Q1 2026 (-140 bps year-over-year) and Toronto 15.5% (-270 bps year-over-year) with six consecutive quarters of positive net absorption downtown per Altus, framing a market where KW Class A downtown is closer to Toronto's recovery than to Ottawa's continued weakness. See GTA office cap rate compression 2026 for the Toronto-side detail.
Multifamily. KW Multifamily High Rise A at 4.50-4.75% brackets the national CBRE High Rise A average of 4.51%, and CBRE names Kitchener-Waterloo among the markets that led Q1 2026 multifamily cap rate increases - structural rental demand in the Kitchener-Cambridge-Waterloo CMA remains the underpinning. Low Rise A and New Construction sit in the same 4.50-5.25% band. CMHC's 2026 housing-market outlook shows another year of strong purpose-built rental apartment starts in the KW-CMA partially offsetting a condo-led decline in total starts, with condominium investor demand weak - a divergence worth flagging in any KW multifamily appraisal.
Retail. KW Retail Strip (anchored) at 5.50-6.35% is among the tighter retail prints in the KW envelope, consistent with Altus's eight-consecutive-quarter ranking of food-anchored retail strip as the top national product-market combination. Regional and Power Centre at 6.00-6.50% sit in line with the Altus Tier I regional benchmark of 6.44% in Q4 2025.
Why a Kitchener-anchored AACI practice reads this market differently than a Toronto practitioner does
The numbers above are public. The reading is not. The CBRE table tells a Toronto-based practitioner that KW Industrial A is at 5.75-6.50%; it does not tell them that iPort Cambridge and iPort Franklin are two-stage developments whose delivery cadence shapes the Cambridge submarket separately from the Kitchener and Waterloo industrial nodes, or which sub-corridors of Kitchener and Waterloo have absorbed purpose-built rental supply ahead of the condo trajectory.
This is the work of a Kitchener-Waterloo practice since 1973. Our firm - City Management and Appraisals, founded in 1973 and trading as Appraisals.on.ca - has read the KW commercial market across four full cycles. CUSPAP 2026 income-approach work demands triangulation across direct-comparison evidence, cap-rate envelopes, and rent-roll specifics. A Toronto practitioner can read the CBRE Q1 2026 report; a Kitchener-anchored AACI practitioner reads it alongside the named-building, named-park supply picture and four cycles of comparable evidence inside the region. That is the difference between a citation and a defensible valuation.
Frequently asked questions
What is the cap rate for Class A office in Kitchener in 2026?
Downtown Class A office in Kitchener-Waterloo was 6.00-6.75% in Q1 2026 per CBRE; Suburban Class A was 6.50-7.50%. KW does not have a Downtown Class AA series in the CBRE national report - Class A is the top of the KW office stack. These are the most recent published city-level figures.
Is Cambridge tracked separately from Kitchener-Waterloo?
No. Cambridge rolls up into CBRE's Kitchener-Waterloo bucket and into Altus's Southwestern Ontario industrial block. Cambridge supply, however, is tracked in named-park detail by Waterloo EDC - iPort Cambridge, iPort Franklin, The Link Cambridge, and IP Park are the principal active sites. A Cambridge valuation triangulates from the KW envelope, the Southwestern Ontario figures, and direct-comparison evidence from Cambridge transactions.
How does Kitchener-Waterloo compare to Toronto on cap rates?
KW trades wider than Toronto across office and industrial. Toronto Downtown Class AA office at 5.25-7.75% has no KW equivalent - KW has no AA. Toronto Industrial Class A at 5.00-5.25% trades roughly 75-125 bps tighter than KW Industrial Class A at 5.75-6.50%. Multifamily is where KW and Toronto sit closest - KW High Rise A at 4.50-4.75% brackets the CBRE national average of 4.51%.
What is driving KW industrial demand in 2026?
Supply discipline plus regional manufacturing resilience. Southwestern Ontario industrial availability fell 40 bps year-over-year to 7.2% in Q1 2026 per Altus - the only region in Altus's Q1 2026 industrial update to post a year-over-year decrease - even as Q1 2026 completions delivered roughly 424,000 square feet at ~75% availability. The Waterloo EDC pipeline (iPort Cambridge, iPort Franklin, The Link, IP Park, Generation Park, 400 Bridge Street, Wilmot) is delivering Class A logistics product into a market that is absorbing it.
Further reading
- Ontario commercial cap rates - the cross-Ontario pillar synthesis with the full CBRE / Altus table by asset class and city.
- Cambridge commercial real estate market - the Cambridge-segment-of-KW analysis grounded in named-park supply data.
- Guelph commercial real estate market - the KW + London Southwestern Ontario triangulation for Guelph.
- Ontario industrial cap rate trends - the Toronto-tight, Southwestern-Ontario-improving cross-Ontario industrial picture.
- Canadian CRE refinance cycle - the 2021 five-year wall, the bid-ask gap, and the underwriting context KW lenders are reading the cap rate table against.
Commission a KW commercial appraisal. If you need a CUSPAP 2026-compliant commercial appraisal in Kitchener, Waterloo, Cambridge, or Guelph - signed by an AACI-designated practitioner from a firm that has read this market since 1973 - request a KW commercial appraisal.
Update log: 2026-05-14 - Initial publication. Kitchener-Waterloo cap rate envelope sourced from CBRE Q4 2025 Canadian Cap Rate Report PDF; regional industrial figures from Altus Group Q1 2026 Canadian Industrial Market Update (May 1, 2026); national office figures from Altus Q1 2026 Canadian Office Market Update (April 22, 2026); national headline from CBRE Q1 2026 Canadian Cap Rates and Investment Insights (April 21, 2026); JLL Q1 2026 Canada Industrial cited for definitional contrast. KW-specific supply pipeline grounded in Waterloo EDC. 2026-05-21 - KW Hospitality (Downtown Full Service) 8.00-9.25% added from CBRE Q4 2025 PDF. Toronto Downtown A/B national comparison columns updated from CBRE Q4 2025 PDF. 2026-07-15 - Re-baselined to CBRE Q1 2026 Canadian Cap Rates and Investment Insights (April 21, 2026): KW Multifamily High Rise A updated to 4.50-4.75% (High Rise B 4.50-5.00%, Low Rise A 4.50-5.25%, New Construction 4.50-4.75%) and Industrial Class B to 5.75-6.50%; national per-class averages updated to Q1 2026; Toronto Downtown AA comparison corrected to 5.25-7.75%; Toronto industrial superlative qualified (Vancouver Industrial A at 4.50-5.25% prints lower); Waterloo EDC attribution corrected (105 Allendale Road is The Link, within Cambridge's IP Park); CBRE Q4 2025 PDF links replaced with the CBRE Q1 2026 report page.